

Rain Instant Pay analysis by Appwee
If your employer offers Rain, the app can turn part of your earned pay into something you can access before the normal payday. I reviewed Rain Instant Pay with a practical question in mind: is it easy for different people to understand and use when money feels urgent? My answer is generally positive, but with an important condition: its usefulness depends heavily on whether your employer participates and whether the available pay arrangement fits your personal budget.
Rain is a free business app from Rain Technologies Inc, built around employer-linked instant pay rather than general banking. That distinction matters. I would not approach it as a replacement for a full bank account, a budgeting app, or a broad payroll service. Its role is narrower and more immediate: help eligible workers unlock employer benefits connected with their pay. The app has reached over 500 thousand installs and holds a 4.7 average from around 34 thousand ratings, which suggests that many users find the central idea straightforward and worthwhile.
In everyday use, the appeal is easy to understand. Imagine a bill arriving several days before payday, a prescription needing to be collected, or a commute becoming more expensive than expected. Instead of relying immediately on a high-cost short-term loan, an eligible worker may be able to access available earnings through Rain. That can reduce pressure, although it does not create extra income. It changes timing, and that difference should remain clear before anyone depends on it.
How Rain Instant Pay feels to use in real life
Readability and navigation for a money-related task
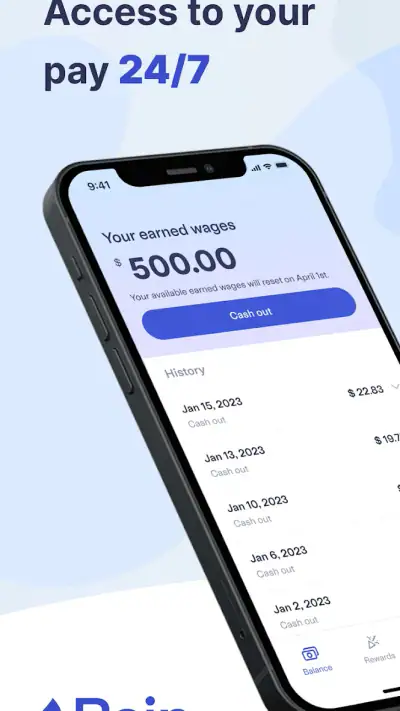
Financial apps need to be especially clear because a small misunderstanding can affect rent, food, or transport. Rain’s focused purpose works in its favor. Compared with a traditional banking app filled with account types, transfers, cards, statements, and promotional panels, an employer-linked pay app has a more limited job to explain. I found that the most useful way to approach it is to look for the current available-pay information first, then check the consequences of requesting access before confirming anything.
The wording around money deserves more attention than the visual polish. I would read every amount as “pay available now,” not “extra money.” That mental habit prevents one of the most common mistakes with early-pay services: treating an advance as a raise. The next payday can feel smaller because some earnings have already been made available. Anyone helping a relative or coworker set up the app should explain that point in plain language rather than simply saying that Rain provides instant pay.
For users who are comfortable with smartphones, the focused workflow can feel less intimidating than managing payroll through a desktop portal. A person who only wants to check whether funds are available does not need to learn a large financial dashboard. That simplicity is valuable for people with limited time, limited digital confidence, or a stressful reason for opening the app.
At the same time, a simple purpose does not guarantee that every user will understand the employer connection immediately. Before spending time troubleshooting, I would confirm that the workplace actually supports Rain and that the employee information being entered matches payroll records. In employer-based services, a login problem may not be an ordinary password problem. It can be an eligibility or enrollment issue, and recognizing that early can save repeated attempts.
My practical tip is to review the app when you are calm, not for the first time during an emergency. Check how the balance is presented, where support information appears, and what confirmation screens say. That small preparation makes the app more useful for someone who reads slowly, becomes anxious around financial decisions, or needs another person to assist without taking over the account.
Motor and sensory considerations
Rain is most approachable for people who can comfortably operate a touchscreen and read financial text on a mobile display. Its focused purpose may reduce the number of screens a user must navigate compared with a full payroll website, which can help someone with limited attention or fatigue. A short, familiar action is easier to repeat than a long administrative process.
However, I would not describe the experience as universally accessible based only on its existence on a phone. People with low vision may need larger system text, stronger contrast, or a screen reader to make the interface comfortable. People with tremors, reduced dexterity, or difficulty making precise taps may find confirmation controls demanding if they are close together. Users with hearing loss should not have to rely on sound alone for important status information, while users sensitive to motion may prefer a calmer presentation if animated transitions are present.
The safest approach is to use the phone’s own accessibility settings and then test a low-risk part of the journey before requesting money. Increase text size if needed, use spoken output where helpful, and avoid rushing through a confirmation screen. If a trusted support person assists, I recommend having the account holder make the final decision and verify the amount personally. That protects both independence and privacy.
There is also a cognitive accessibility angle. Early access to wages can be emotionally appealing, especially when someone is under financial pressure. A clear personal rule helps: use Rain only for a defined need, note the amount accessed, and check what remains for the regular payday. Writing that information in a paper notebook or a separate budgeting tool can be easier than trying to remember it from the app alone.
For users with reading difficulties, I would avoid interpreting labels from memory. Read the full screen, pause at the final confirmation, and ask a trusted person to explain unfamiliar payroll terms without making the decision for you. The app’s narrow purpose helps, but financial vocabulary can still create a barrier even when navigation itself feels simple.
Situational access beyond the ideal setup
Rain makes the most sense for workers whose pay is already connected to a participating employer and who have reliable access to their phone. In that situation, it can be useful during a gap between an expense and payday. A worker facing an unexpected travel cost might use it to keep getting to work, while someone managing variable household expenses might use it sparingly to avoid a more expensive borrowing option.
That convenience changes when the phone is shared, the connection is unreliable, or the user is working in a noisy or distracting environment. A person may be able to open the app but still lack the privacy needed to review a sensitive balance. I would avoid requesting pay while standing in a crowded workplace, using someone else’s device, or relying on a hurried conversation. Financial access should happen in a setting where the amount and destination can be checked carefully.
Rain may also be helpful for people who prefer mobile tools over paper forms or a desktop payroll portal. A phone is often closer at hand than a computer, and that can matter for workers with changing schedules or limited access to office systems. Still, mobile convenience should not be confused with universal availability. If the employer does not support the service, the app cannot solve that problem by itself.
One non-obvious use is preparation for fluctuating weeks. Rather than opening the app only when a crisis appears, a worker can use it as a prompt to compare an upcoming expense with the expected regular paycheck. If early access would leave too little for fixed bills, the better decision may be not to use it. In that sense, Rain works best as a controlled timing tool, not as an automatic response to every shortfall.
Another useful scenario involves a helper supporting an older worker, a person with a disability, or someone who is still learning English. The helper can assist with reading and navigation while the account holder stays in control of the phone, verification details, and final request. This arrangement is more inclusive than handing over the entire process, and it reduces the risk of exposing financial information unnecessarily.
Where the usual alternatives may be better
Rain occupies a specific space between payroll access and short-term financial management. A normal bank account is better for holding money, paying bills, reviewing transaction history, and building a broader view of household finances. A budgeting app is better for planning several weeks ahead, categorizing expenses, and seeing patterns. An employer payroll portal may be better for official pay statements, tax information, and detailed employment records.
A credit card or personal loan may offer a larger amount or a longer repayment structure, but those options can introduce interest, fees, or debt that lasts beyond the immediate problem. Rain’s strength is that it is tied to wages already earned rather than asking the user to borrow against an unrelated credit limit. Its weakness is equally important: it cannot replace income and may make the next payday harder to manage if used casually.
For someone who only needs occasional early access and whose employer supports the service, Rain can be more direct than applying for credit. For someone trying to escape a recurring monthly deficit, it is probably the wrong tool. Repeatedly moving pay forward can hide the underlying gap and create a cycle in which every payday is already partly committed. In that situation, a budget review, employer payroll conversation, or qualified financial counselor would be more appropriate.
The app is also not the best choice for a user who wants a complete financial picture in one place. Its value comes from a focused employer benefit, not from replacing every money-management function. I would keep using a bank or budgeting tool alongside it rather than expecting Rain to provide long-term planning.
Remaining barriers that affect inclusion
The biggest barrier is eligibility. A beautifully designed mobile experience would still be irrelevant to a worker whose employer does not offer the benefit. That employer dependency also means two people with similar financial needs may have very different access. One may be able to use Rain while another must wait for the normal payroll schedule or seek a different solution.
There is a second barrier in understanding the relationship between available pay and the next paycheck. Users who have limited financial literacy, memory difficulties, or language barriers may focus on the amount visible today and overlook the later effect. I would treat the confirmation step as a budgeting decision, not a simple withdrawal. If the app presents terms or timing that are unclear, stop and seek an explanation rather than guessing.
Privacy can be a practical accessibility issue too. A person who relies on a family member, interpreter, job coach, or support worker may need help entering information. That assistance can be useful, but it also creates a risk that someone else sees balances or controls the request. The most inclusive workflow is one that preserves the user’s ability to review each detail and say yes or no.
Technical friction can be especially serious when the app is needed urgently. A failed sign-in, an employer-record mismatch, or an unclear status message may affect someone who has no spare time, data, or confidence to try again. I recommend setting up the app before an emergency, keeping employer payroll details available, and recording support instructions somewhere accessible. Those steps do not remove every obstacle, but they make a stressful moment less dependent on memory.
Finally, early-pay products can be unsuitable for people whose income is already too low for essential bills. The ability to access money sooner may feel empowering while still worsening the following week. Rain should be used with a specific plan for the full pay period. If the plan depends on accessing pay repeatedly, that is a sign to look for a more sustainable solution.
What I would check before relying on it
I would begin by asking the employer whether Rain is available and how the benefit fits into the normal payroll process. Then I would install the current release, version 2.7.1, and take time to understand the screens before making a request. The app is free to install, but “free” does not mean that the broader financial decision has no cost; the important question is how accessing pay now affects later cash flow.
I would also decide in advance what amount would solve the immediate problem and what amount must remain protected for essentials. That limit is more useful than opening the app and choosing whatever maximum appears available. After any request, I would note the amount and expected effect on the next payday in the same place where I track bills.
For a user with accessibility needs, I would test text size, screen reading, touch accuracy, and privacy with a small, non-urgent interaction. If the app is difficult to read or operate, the problem should be addressed before there is a deadline. A trusted helper can make the process easier, but the user should retain control of authentication and approval.
The Everyone content rating makes the app broadly suitable from an age-rating perspective, but that does not mean every financial situation is suitable for instant pay. Younger or inexperienced users may need extra guidance about budgeting and the difference between earned wages and new money. I would explain that distinction before recommending it to anyone who has not managed a regular paycheck independently.
My inclusive verdict
I see Rain as a useful, focused option for eligible employees who need more control over the timing of earned pay. Its narrow purpose can make it less overwhelming than a full financial platform, and mobile access may help people who cannot conveniently use a desktop payroll system. The strong 4.7 average and broad user adoption are encouraging signs, although personal suitability matters more than popularity.
From an inclusion perspective, the app is strongest when the user has a participating employer, a private phone, reliable access, and enough financial breathing room to use early pay selectively. It is less suitable when the user needs long-term budgeting, detailed payroll records, larger borrowing, or a solution to recurring income problems. People with visual, motor, hearing, cognitive, or language-related needs may be able to use it with device settings and trusted assistance, but I would not assume that every interaction will be effortless.
My recommendation is conditional but clear: try Rain if your employer provides it, you understand the effect on your next paycheck, and you have a specific reason for accessing money early. Use it as a timing aid, not as a substitute for income or planning. If that boundary is respected, Rain Technologies Inc has created a practical business app that can genuinely reduce short-term friction for many workers while still leaving room for users to make careful, informed decisions.
Gallery
Rain Instant Pay Pros and Cons
- Fast access to earned wages after eligible shifts.
- Helps manage cash flow between regular paydays.
- Simple mobile access to payment information.
- May reduce reliance on costly short-term borrowing.
- Useful for workers with variable schedules or income.
- Availability depends on employer participation and eligibility.
- Instant transfers may include transaction or service fees.
- Not every shift or earning type may qualify for early pay.
- Payment delays can occur because of payroll verification.
- Frequent use may make budgeting around payday harder.
Rain Instant Pay Frequently Asked Questions
What is Rain Instant Pay, and how does it work?
Rain Instant Pay is a financial service that may allow eligible users to access part of their earned wages before the regular payday, depending on employer participation and account eligibility. After signing in, users can review available earnings, choose an amount, and request a transfer. Availability, processing times, and supported features can vary by employer, location, and the terms shown inside the app.
Who can use Rain Instant Pay?
Access to Rain Instant Pay is generally dependent on whether your employer offers the service and whether you meet its eligibility requirements. The app may verify employment information, earned wages, identity, and account details before allowing transfers. Not every employee, contractor, or location is supported, so it is best to confirm participation with your employer and carefully review the eligibility information during registration.
How quickly does money arrive after requesting an advance?
Transfer speed depends on the delivery method selected, your bank or debit card, the employer’s payroll information, and whether the request is made during business or processing hours. Some transfers may arrive quickly, while standard delivery can take longer. Before confirming a request, Rain should display the expected arrival time and any applicable costs, so check those details carefully.
Are there fees or other costs for using Rain Instant Pay?
Depending on the features available to your account, Rain Instant Pay may offer different transfer options with different pricing. Faster delivery, card-related services, or optional features may involve fees, while other methods could be free or have separate conditions. Review the final confirmation screen, fee disclosures, subscription terms, and transfer limits before accepting any transaction.
Is Rain Instant Pay safe to use, and what information does it require?
A wage-access app typically needs personal, employment, banking, or debit-card information to verify your identity and deliver funds. Before using Rain Instant Pay, review its privacy policy, security information, permissions, and terms of service. Use a strong password, enable available security controls, and download the app only from an official store or a link provided by your employer.














